

Concora Credit
by Concora Credit
3.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
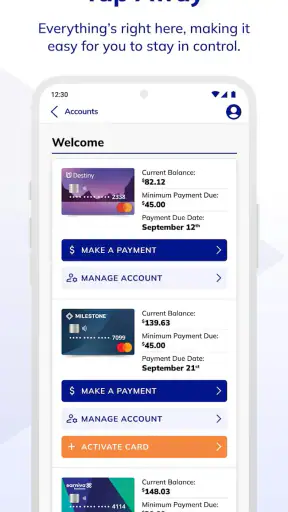
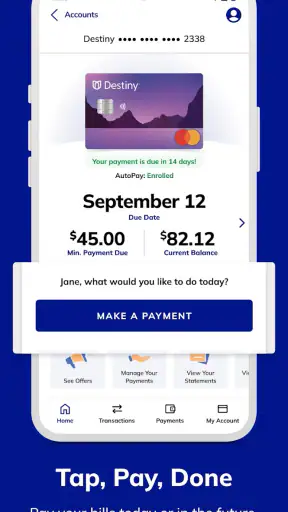
 Analysis by Getfullapps
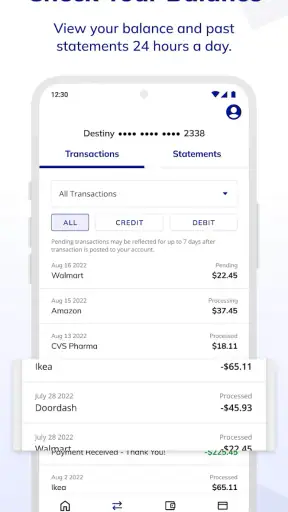
Managing a credit account is rarely something I want to turn into a daily project. I usually want a quick way to check what I owe, review recent activity, and handle an account without searching through emails or keeping a browser tab open. That is the role Concora Credit aims to fill: it is a free finance app from Concora Credit for managing eligible account information from a phone.
My view is fairly practical. This is not a general budgeting tool, a full banking replacement, or an app I would choose to organize every part of my financial life. Its value depends on whether I already have a Concora Credit account and want a more convenient mobile access point. For that audience, the focused design can be useful. For someone looking for spending categories, investment tracking, bill planning, or a single dashboard for several unrelated financial institutions, the usual banking or budgeting alternatives are likely a better match.
What I would check before choosing it
I would use this section to make a quick decision before installing: first, confirm that the account you want to manage is a Concora Credit account, then consider whether phone-based access fits your routine. I’d also think about what I expect the app to replace; it may simplify account checks without taking over budgeting or banking. With that in mind, the next question is where it earns a regular place in my day.
The first question is whether it matches your account
The most important decision criterion is not the app’s appearance; it is the relationship between the app and the account I need to manage. Since the developer is Concora Credit and the store summary centers on managing Concora Credit account accounts, I would install it when I already use that service. I would not download it expecting it to connect every credit card, checking account, or loan I have.
That distinction saves time. A dedicated account app can be more direct than a broad personal-finance platform, but it also has a narrower purpose. If my goal is simply to keep an eye on one relevant account, a focused tool makes sense. If I want a complete picture of household money, I would begin with my bank’s app or a budgeting service designed to combine multiple providers.
My practical test for usefulness
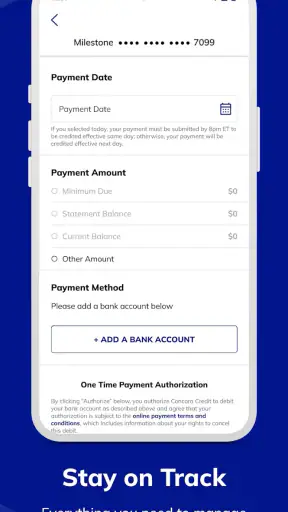
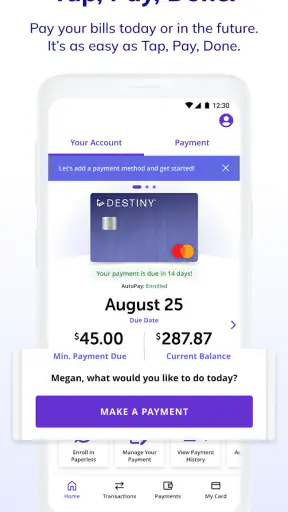
I would judge the app by how quickly it helps me answer three everyday questions: what is happening on the account, what action needs my attention, and whether I can complete that action without moving to another device. The app’s usefulness rises when it reduces those small moments of friction.
For example, imagine I am standing in a shop and want to check whether a recent payment has appeared before making another purchase. I do not need charts or a long financial report in that moment. I need a clear account view and confidence that I am looking at the right information. Later, at home, I might use the same app to review activity more carefully and decide whether a payment or account check needs follow-up.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That is a modest use case, but it is the right way to think about this product. It is an account-management companion, not a financial coach. I would value reliable access and clear navigation more than decorative tools that do not help me handle the account itself.
Access, compatibility, and expectations
The app is free to download and carries an Everyone content rating, which makes it approachable for a broad audience. It was released on June 21, 2023, and the current version is 3.0.16. It supports devices running Android 7.1 or later, so I would still check the operating system on an older phone before planning around it.
Its average rating is 3.4 from around 3.4 thousand ratings, with roughly 1.6 thousand written reviews. I treat that as a reason to keep expectations balanced rather than as an automatic rejection. A finance app can be genuinely useful for one account holder and frustrating for another, especially when the person expects the broader feature set of a bank or budgeting platform.
The app has passed one million installs, so it is not an obscure tool used by only a handful of people. Still, popularity does not change the central question: does it give me the account access I actually need? I would answer that before considering the install count or rating.
What I would prepare before using it
I would have my account credentials available and make sure I am downloading the official app associated with Concora Credit. I would also avoid treating the first successful sign-in as the end of the setup process. My first session would be a short orientation: confirm that the account shown is mine, look at the available account areas, review how recent activity is presented, and identify where routine account actions are located.
This is a small but useful habit. When I am in a hurry later, I do not want to explore unfamiliar screens while trying to resolve a payment question. A two-minute inspection during setup can make the app feel much faster during real use.
Where Concora Credit works best
For me, the best fit is a focused routine: checking an account when I’m away from my computer, then reviewing anything unusual against receipts or my own budget. I’d keep broader money planning in the tool I already trust, rather than duplicating records here. That division makes the app’s recurring role clearer and helps show when its convenience is genuinely useful.
A focused alternative to repeated browser visits
The strongest argument for this app is convenience. A dedicated mobile app can be easier to reach than opening a browser, finding the correct page, and signing in through a general website. That matters when I check an account several times during a billing period or when I want to verify activity away from my computer.
I also prefer a focused account view when I am trying to avoid distractions. A broad financial app may show balances, spending categories, savings goals, and promotional content all at once. That can be helpful for planning, but it can also bury the one account detail I came to inspect. Concora Credit’s narrow purpose is a strength when I want a direct route to the relevant account.
Useful for a simple checking routine
I would use it as part of a short weekly routine rather than constantly refreshing it. I might open it after reviewing my household budget, check recent account movement, and note anything I do not recognize. If I am monitoring a purchase or waiting for a payment-related update, I can use the app as a convenient checkpoint instead of relying on memory.
The non-obvious benefit here is not a special feature; it is separation. I can keep general budgeting in one place and use the dedicated app for the account that needs direct attention. That reduces the temptation to mistake a total from a budgeting service for the current account information shown by the account provider itself.
Why the developer matters in this case
Because Concora Credit is also the developer, the app has a clear connection to the service it represents. I find that more reassuring than an unrelated third-party tool that asks me to bring several financial accounts into one interface. A direct provider app may be the simpler choice for someone who does not want to manage account connections across multiple services.
That does not mean I would stop using every other financial tool. I would still use a separate bank app for banking tasks and perhaps a spreadsheet for a household plan. The advantage is that this app can occupy one defined place in that setup instead of trying to replace everything.
Small workflow improvements I would recommend
My first tip is to decide what the app is for before opening it. If I am checking one account, I go in with a specific question: has the activity changed, do I need to review something, or am I preparing to make a payment decision? That keeps a quick check from becoming aimless scrolling.
My second tip is to compare the app view with my own records when something looks unexpected. I would not immediately assume that a confusing entry is an error, but I would note the date and amount, then compare it with receipts, email confirmations, or my budget. This is especially useful when I am tracking several purchases close together.
My third tip is to use the app as a monitoring tool, not as permission to spend more. Easy mobile access can make an account feel more manageable than it really is. I would still keep a separate spending limit and review the overall effect on my monthly plan. Convenience should improve awareness, not encourage casual borrowing.
Where the experience may feel limited
The same focus that makes the app straightforward can make it feel incomplete. If I expect a full financial dashboard, I may quickly run into the boundaries of a dedicated account manager. I would not choose it as my only tool for tracking groceries, rent, savings, investments, or accounts from several providers.
I would also keep a second route available for important account tasks. That is not a criticism unique to this app; financial access is too important to depend on one interface without a backup habit. If the app is unavailable or I need information presented differently, I want to know how I will continue managing the account through the service’s other normal channel.
Another point is that the app’s rating suggests a mixed experience among users. I would not turn that into a prediction about my own session, but I would install it with a sensible test period. After signing in, I would check whether navigation is clear on my phone, whether account information is easy for me to interpret, and whether the workflow suits the way I normally manage credit.
When a broader alternative fits better
A traditional banking app is usually the better choice when most of my money is already held with one bank and I want checking, savings, transfers, and credit information in one place. A budgeting app is a better fit when my main challenge is understanding spending across several accounts. A spreadsheet may be better for someone who wants complete control over categories and does not mind entering information manually.
I would also look at the usual provider website if I manage accounts from a desktop throughout the day. A mobile app offers portability, but a larger screen can be more comfortable for careful review, record keeping, or comparing several months of information. The right choice depends on where I actually perform these tasks, not on whether an app is available.
The cost of switching is mostly organizational
Since the app is free, the main cost of trying it is not a purchase. It is the time spent learning another sign-in route and deciding which tool should be the source of truth for different tasks. I would avoid copying every detail into multiple apps just because I installed a new one. That creates conflicting records and makes financial decisions harder.
Instead, I would assign clear jobs. Concora Credit would be for direct account management and account-specific checking. My bank app would remain the place for banking activity if needed. A budget or spreadsheet would cover the wider household picture. This arrangement keeps the switch small and prevents the app from becoming another duplicate dashboard.
I would also review whether notifications, saved credentials, or device access fit my personal security habits before relying on the app regularly. I would use the phone’s normal security protections, avoid sharing access, and sign out or review device access if I change phones. These are sensible precautions for any finance app, but they matter more when the app provides a direct path to an account.
Who should use it and who should skip it
I would recommend giving it a try if I already have a Concora Credit account, prefer handling routine checks on a phone, and want a provider-focused alternative to repeated browser visits. It is also reasonable for someone who wants a dedicated app without paying for a separate budgeting service.
I would skip it if I am searching for a complete money-management system, need one place for unrelated financial institutions, or mainly want detailed spending analysis. In those situations, installing a narrow account app may add another step rather than remove one. I would also be cautious if my phone runs an older system below Android 7.1, because compatibility is a basic requirement before any feature comparison matters.
My recommendation after weighing the alternatives
My recommendation is conditional but positive: use Concora Credit when your need is specifically managing a Concora Credit account from a mobile device. The free price and focused purpose make it a low-risk option to test, and its direct connection to the developer’s service is more relevant than a long list of unrelated financial tools.
I would not present it as a replacement for a bank app or a budgeting platform. Its best role is narrower and more practical: a convenient account window that helps me check activity and stay connected to the credit service I already use. That can be enough, especially for quick checks during the day or a regular review routine.
Before committing to it as part of my financial habits, I would sign in, verify that the account information is presented clearly, and try the actions I expect to use most. If those basic steps feel comfortable, the app earns a place on my phone. If I need broader planning, I would pair it with a budgeting tool rather than forcing it to do a job it was not designed to handle.
Overall, I see Concora Credit as a sensible specialist rather than an all-purpose finance solution. Its value comes from reducing access friction for the right account holder. If direct account management is your goal, it is worth testing; if complete financial organization is your goal, choose a broader companion instead.
Pros
- User-friendly interface for easy navigation.
- Secure encryption for data protection.
- Quick and seamless loan application process.,24/7 customer support available.
- Low interest rates compared to competitors.
Cons
- Limited availability in certain regions.
- Requires a stable internet connection.
- Occasional app crashes reported.
- Lengthy verification process for new users.
- Limited features in the free version.
FAQs for Concora Credit
What is Concora Credit, and how does it work?
Concora Credit is a financial management app designed to help users track their credit scores, monitor financial health, and manage debts efficiently. The app provides tools for budgeting, alerts for due payments, and insights into spending habits. Users can link their bank accounts for a comprehensive overview of their financial status.
Is Concora Credit free to use, or are there any subscription fees?
Concora Credit offers a free version with basic features, including credit score monitoring and budgeting tools. However, for advanced features like personalized financial advice and detailed spending analytics, users may need to subscribe to a premium plan. Pricing details can be found within the app or on the official website.
How secure is my personal and financial information on Concora Credit?
Security is a top priority for Concora Credit. The app uses advanced encryption protocols to protect user data. Additionally, it employs two-factor authentication and regular security audits to ensure that personal and financial information remains secure. Users can review the app's privacy policy for more details.
Can I link multiple bank accounts to Concora Credit?
Yes, Concora Credit allows users to link multiple bank accounts to provide a consolidated view of their financial status. This feature helps users track spending across different accounts, manage budgets effectively, and receive insights into their overall financial health.
Does Concora Credit impact my credit score when I use it?
Using Concora Credit to monitor your credit score does not impact your credit rating. The app performs a 'soft pull' on your credit report, which does not affect your score. It's designed to help users stay informed about their credit status without any negative repercussions on their credit score.

Concora Credit
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via AppTeam@concoracredit.com, visit https://about.concoracredit.com/contact-us, or review their https://about.concoracredit.com/app-privacy-policy.










